The country’s investment citizenship framework illustrates why applicants must evaluate authorized agents, qualifying contributions and government due diligence before proceeding, particularly as officials negotiate the program’s eventual phaseout.
WASHINGTON, DC, November 21, 2026: Citizenship by investment in St. Kitts and Nevis remains available during a government-announced transition, but prospective applicants must complete financial disclosure, identity verification, and background investigations before any qualifying contribution can lead to a nationality decision.
The federation’s long-established program now operates amid international scrutiny and a newly announced plan for an orderly wind-down, making the accuracy of application records and the status of official investment routes especially consequential for families evaluating second citizenship.
For investors considering a Caribbean passport, the key distinction is between eligibility to submit an application and final government approval, because meeting an advertised financial minimum does not override screening requirements or guarantee a timetable.
A November Announcement Changes the Program’s Outlook
Prime Minister Terrance Drew announced on November 13 that St. Kitts and Nevis would wind down citizenship by investment on a timetable being negotiated with the European Union, citing potential harm to international banking relationships and passport mobility.
A November 13 Caribbean Media Corporation report on the planned phaseout described the government’s intention to maintain strict application standards during the transition, while officials continued discussing the final date for receiving new citizenship files.
As of November 16, the government had not announced a final application cutoff, and the Citizenship Unit’s published process remained operative, making it inaccurate to claim that applications were already prohibited or that an agreed closure date existed.
Citizenship Remains a Sovereign Government Decision
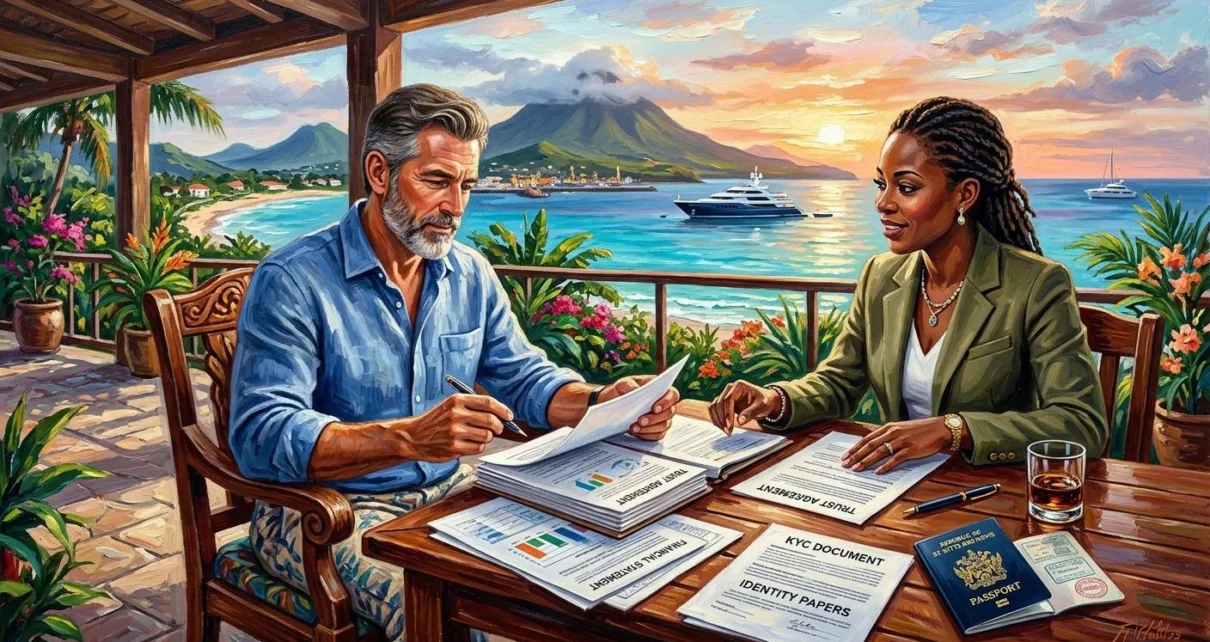
The country’s Citizenship Unit administers applications under national law, while qualified private representatives help assemble files and communicate with officials but have no authority to grant nationality or bypass legally required investigations.
The program lets applicants pursue a government-approved investment route rather than ordinary residence-based naturalization, but acquiring citizenship still requires the relevant authority to accept identity, financial, security, and other eligibility evidence relevant to the decision.
A prospective investor should therefore treat an agency’s preliminary approval or commercial promise as different from official approval in principle, and should not describe any future passport as secured before completing the prescribed governmental procedure.
Only Approved Authorized Agents Can Submit Applications
St. Kitts and Nevis requires applications to pass through an Authorized Agent recognized by its Citizenship Unit, and individuals cannot mail completed dossiers directly to the government for independent processing.
The official agent register lists approved local professionals and firms, while the government separately lists international marketing agents whose promotional role does not entitle them to bypass the authorized submission channel required under current operating rules.
Applicants should verify the current name and status of the specific submitting entity, particularly when negotiating with an overseas marketer or consultant whose business registration alone does not prove authorization by the Citizenship Unit.
Agent Verification Includes Negative Regulatory Information
The Citizenship Unit also publishes information about blacklisted, suspended and otherwise restricted representatives, reinforcing why an attractive quotation or professional-looking website should never substitute for checking the government’s current official list of eligible agents.
An agent may once have held authorization but later face restrictions, so the key question is whether the representative remains eligible to submit applications when the file is presented, rather than whether credentials existed historically.
Prospective clients should obtain a written engagement identifying the authorized local agent, the service provider collecting fees and the party receiving funds, with responsibilities clearly separated before confidential records are supplied to any third party.
The Sustainable Island State Contribution Starts at $250,000
The Sustainable Island State Contribution currently sets a minimum of $250,000 for a principal applicant or a qualifying family of up to four, directing money toward national development priorities under the designated government framework.
Additional qualifying dependants increase the required amount, with the published contribution schedule distinguishing children younger than eighteen from older family members, while due diligence charges and other application expenses remain separate from the contribution itself.
Because the contribution is intended for public development rather than a personally owned asset, applicants should examine the written payment conditions and potential nonrefundable expenses before regarding the advertised minimum as a recoverable investment.
A Public Benefit Option Offers Another Qualifying Route
The Public Benefit Option also carries a published minimum contribution of $250,000 for specified applications, supporting approved projects whose financial terms and legal classification must be confirmed through the authorized official process.
This option should not be confused with a conventional private real estate purchase, because the government’s rules concerning the recipient and recognized project differ from those applied to ownership interests in approved developments.
Applicants should request authentic project descriptions and current official confirmation before committing to a particular beneficiary, rather than assume that any proposed school, housing initiative or charitable payment qualifies for the citizenship program.
Real Estate Routes Have Higher Published Thresholds
The Developer’s Real Estate Investment Option currently begins at $325,000 for a qualifying interest in an approved development, with published rules generally requiring the investment to be held for at least seven years before resale.
The separate Private Real Estate Investment Option identifies $325,000 for qualifying condominium interests and $600,000 for designated single-family homes, subject to approved property status and the applicable ownership and holding requirements.
Government approval of an investment route does not guarantee a developer’s construction schedule, rental income or future sale price, so independent property due diligence remains necessary alongside the separate citizenship investigation of the proposed principal applicant.
Administrative and Screening Fees Add to the Cost
The Citizenship Unit lists due diligence charges of $10,000 for the principal applicant and $7,500 for each qualifying dependant aged sixteen or older, alongside further route-specific and post-approval fees where applicable.
Real estate applicants may additionally face legal, conveyancing, insurance and project costs, making total financial exposure for investors and accompanying family members materially different from the headline purchase threshold presented in commercial advertisements.
An accurate family quotation should distinguish official government charges, actual investment amounts and professional service fees, identifying which payments could remain due or nonrefundable if background investigators reach an unfavorable decision on the merits.
Source of Wealth Differs From Source of Funds
Source of wealth explains how the applicant accumulated assets over time, while source of funds identifies the precise money transferred to complete the contribution or purchase, and a credible file should reconcile the two financial narratives.
Business profits, employment savings, inheritance, investment returns, and property sales can provide legitimate explanations, but their acceptability depends on reliable supporting records showing how lawful proceeds moved into the accounts used for citizenship expenses.
A large account balance without an intelligible history may leave important questions unanswered, just as an impressive business valuation does not necessarily demonstrate that the applicant personally controls the cash intended for transfer.
Entrepreneurs Need a Coherent Corporate Record
Company founders may need to explain share ownership, audited or management accounts, tax filings, dividends and major transactions, especially when the business operates across jurisdictions or retains profits through a complex corporate structure.
Investigators can examine whether a transfer genuinely originated from an enterprise owned by the applicant and whether the amount appears consistent with reported business activity, rather than treating every corporate remittance as automatically legitimate.
Where holding companies or family partnerships are involved, accurate beneficial ownership records and documentary explanations help distinguish lawful arrangements from unexplained layers that obscure who provided the money or controlled the underlying transaction.
Sponsored Applications Face Additional Financial Checks
The Citizenship Unit’s application guidance identifies extra documentation when a parent or child financially sponsors a principal applicant, including relationship records, employment or incorporation evidence, banking information and proof explaining the sponsor’s relationship to the applicant.
Its published requirements also require a twelve-month bank statement and a bank reference letter for such sponsors, and explain that financial supporters undergo due diligence and incur fees beyond those of principal applicants.
This distinction matters for families funding applications collectively, because the person financing the investment may be examined even when that individual is neither seeking a passport nor receiving any corresponding citizenship benefit through the request.
Identity Checks Include Police and Civil Records
The government’s application guidance lists passports, birth certificates, proof of address, police clearances, and medical documentation among the materials it may request, along with evidence establishing the source and intended movement of investment funds.
Applicants with multiple nationalities, lawful name changes or residence histories in several countries should ensure the records tell a consistent story, rather than relying on one recently issued travel document to establish every prior identity.
An old conviction, pending investigation, or previous immigration refusal may require individualized analysis under applicable rules, and a well-prepared application should disclose required information accurately rather than assume financial eligibility removes character concerns.
Interviews Provide a Separate Verification Opportunity
The Citizenship Unit requires principal applicants to attend an interview, while dependants aged sixteen or older may also need to participate, depending on the applicable instructions and the authority’s assessment of their individual circumstances.
Interviews may test the consistency of employment histories, investment explanations and family relationships, giving officials an opportunity during the application process to clarify contradictions between personal statements and documents assembled earlier through authorized representatives.
Applicants should answer independently and truthfully, because a coached account concealing assets or background information can create more serious problems than an honest request for additional records explaining a complicated financial history and related material circumstances.
Approval in Principle Comes Before the Main Investment
Under the government’s published application sequence, the Citizenship Unit conducts screening before issuing an approval-in-principle letter, after which the applicant completes the approved contribution or investment and satisfies remaining fees and documentary requirements before final citizenship issuance.
This sequence should protect applicants from confusing the full qualifying investment with preliminary preparation expenses, although due diligence charges and professional costs may arise earlier and can be subject to separate refund conditions.
A receipt from an agent or a developer’s reservation contract does not establish government approval in principle, so investors should insist on official confirmation before completing the major payment stipulated for their chosen route.
Published Processing Estimates Are Not Guarantees
The Citizenship Unit has described an ordinary review period of roughly 120 to 180 days for many applications, but complex backgrounds, unresolved documents, and additional security inquiries can cause delays beyond public estimates.
Prospective applicants should treat the figure as administrative guidance rather than a contractual nationality delivery date, especially when a policy transition could create new filing instructions or requirements for files still under review.
Government approval, investment completion, citizenship documentation, and passport issuance are distinct milestones, so avoid booking irreversible international arrangements based solely on a preliminary processing estimate.
A Rescinded United States Advisory Needs Accurate Context
The United States Treasury’s Financial Crimes Enforcement Network notice states that its 2014 advisory on potential misuse of St. Kitts and Nevis investor passports was formally rescinded on February 24, 2026, a significant shift in the agency’s published position.
The country’s Citizenship Unit welcomed the withdrawal as recognition of screening reforms, but rescission of that specific advisory does not remove ordinary banking obligations or guarantee that foreign institutions will accept every passport without additional identity checks.
Historical allegations in the archived advisory should not be presented as ongoing Treasury findings, and the government’s account of improved controls should remain open to independent evaluation and ongoing public accountability.
Banking Relationships Influence the Program’s Future
In explaining the November wind-down decision, Prime Minister Drew emphasized that correspondent banking relationships enable local institutions to process payments, support trade and maintain connections with financial partners in the United States and elsewhere.
He warned that international financial restrictions could affect ordinary residents and businesses, citing the protection of those links as a major reason to negotiate a responsible transition rather than preserve investor citizenship indefinitely.
These concerns extend beyond one applicant’s finances, because a bank’s willingness to process international transactions depends on regulatory compliance and commercial risk decisions that national citizenship approval can neither control independently nor compel overseas institutions to disregard.
European Visa Policy Creates Additional Uncertainty
European officials have raised concerns about investor nationality programs that grant passports without a substantial connection to the issuing country, particularly where those passports permit short-term travel into the Schengen area without advance visas.
The government’s decision to negotiate a wind-down reflects pressure from the European Union’s revised visa-suspension framework, although the announcement alone did not establish that existing citizens immediately lost their current travel privileges.
A second passport should therefore be evaluated as a lawful nationality rather than a permanent guarantee of access to every foreign destination, since receiving countries retain the right to set immigration and border policies independently.
Regional Reform Does Not Replace National Responsibility
St. Kitts and Nevis has participated in Eastern Caribbean efforts to harmonize investment thresholds, background investigations, agent oversight and information sharing through a multilateral framework alongside plans for a dedicated regional citizenship-by-investment regulatory authority.
The regional framework may strengthen consistent screening practices, but the country’s own officials remain responsible for issuing citizenship decisions under national law and ensuring that applicable procedures continue throughout any negotiated transition period.
Applicants should distinguish regulatory proposals, enacted legislation and operational systems, because a statement about regional cooperation does not establish that every new verification mechanism has already been implemented in every participating jurisdiction at the relevant filing date.
Family Eligibility Requires Individual Documentation
Government guidance allows qualifying spouses, children and certain dependent parents to be included, but financial support, age and educational conditions differ among categories and must be established through reliable civil and supporting records.
Adult children studying full-time may qualify within defined age limits, while parents aged fifty-five or older can face specific dependence conditions, making an informal assumption about extended family inclusion an unreliable basis for cost planning.
Each person’s identity and background may require separate review, and including a dependent does not eliminate the need to disclose that individual’s previous names, nationalities, or other information requested by officials.
Dual Citizenship Does Not Erase Earlier Obligations
St. Kitts and Nevis recognizes dual citizenship, but a new passport does not automatically end the holder’s existing nationality or remove tax, reporting and legal duties imposed by another country under its own laws.
Foreign banks may continue asking about previous citizenships, residence, beneficial ownership and source of wealth after naturalization, because customer screening is not limited to whichever valid passport an individual chooses to present to the reviewing institution.
Families should examine how a potential additional nationality interacts with children’s citizenship, travel documentation and financial arrangements rather than equate government approval with a complete replacement of earlier legal identities or previously established rights and obligations.
Independent Advice Should Begin With Official Verification
Amicus International Consulting describes second-passport and international mobility advisory services for people exploring lawful nationality options, but no consultant can waive the Citizenship Unit’s agent requirements, financial screening or final decision, or guarantee issuance of a government passport.
A responsible preliminary assessment should identify the authorized submitting agent, the current investment route, required source-of-funds evidence and the practical effect of the announced wind-down before applicants commit substantial resources under the prevailing official rules.
Reject promises of guaranteed approval, secretly discounted contributions, or immunity from due diligence, especially after the prime minister said the transitional period would not become a rushed sale of citizenship.
A Changing Program Makes Documentation More Valuable
Prospective applicants should first establish that an application is still permitted under current official notices, then prepare authentic identity, criminal history and financial records with qualified assistance before choosing a contribution or real estate transaction.
The announcement of a potential phaseout makes timely official updates important, but it does not justify concealing unresolved facts or moving funds outside the required process in response to artificial commercial pressure before eligibility is established.
For St. Kitts and Nevis, the central issue in November 2026 is whether lawful applications can proceed transparently during a negotiated transition, with citizenship decisions grounded in verified backgrounds, legitimate financing and accountable public administration.