Insurance conditions for visa applicants should not automatically apply to every American on a visa-exempt visit.
WASHINGTON, DC, October 27, 2026 — U.S. citizens traveling internationally face different travel insurance requirements depending on their destination, immigration category, and purpose of travel; some governments require proof of medical coverage, while others let ordinary visa-exempt visitors enter without an insurance certificate.
The distinctions have become increasingly important as countries revise tourist admission rules, introduce compulsory medical insurance, and establish separate coverage standards for short-term visas, electronic travel authorizations, residence permits, and long-term immigration programs.
European Schengen visa regulations provide one example of mandatory insurance applying to a particular visa application category, while Georgia’s requirements introduced in January 2026 demonstrate that a government can mandate medical coverage for tourists regardless of whether they need a traditional entry visa.
Cuba offers another distinct example: visitors must carry appropriate medical insurance, with special arrangements affecting Americans arriving on flights from the United States and additional restrictions governing lawful travel to the country.
For American passport holders, understanding these differences can prevent immigration complications and unnecessary insurance purchases while ensuring travelers recognize the difference between legally required coverage and strongly recommended insurance for financial protection.
Travel Insurance Requirements Depend on Immigration Status
International travel insurance regulations can apply through different legal mechanisms, including conditions imposed during visa applications, requirements examined at the border, and obligations associated with residence permits or specialized immigration programs.
Some governments require an insurance certificate before issuing a visa, while others allow travelers to obtain the relevant authorization without insurance but require qualifying medical coverage before admission to the country.
These distinctions matter because a United States citizen entering under a visa exemption may face different requirements from a foreign national applying for a Schengen short-stay visa, even when both travelers intend to visit the same destination.
Insurance obligations can also change by purpose of travel, with students, employees, retirees, and long-term residents sometimes required to maintain coverage different from that expected of ordinary tourists.
The correct approach is therefore to identify the traveler’s nationality, destination, immigration category, and intended duration before determining whether travel insurance is legally required.
Schengen Visa Applicants Face Specific Insurance Requirements
The European Union’s Visa Code establishes travel medical insurance requirements for applicants seeking qualifying Schengen short-stay visas, including provisions concerning emergency medical treatment, hospitalization, medical repatriation, and other specified expenses.
Under Article 15 of the European Union Visa Code, relevant applicants generally must show medical insurance that provides at least €30,000 in coverage throughout the visa territory for the required period.
The regulation also addresses multiple-entry visa applicants, who ordinarily must demonstrate appropriate coverage for their first intended visit while acknowledging the need to maintain qualifying insurance during subsequent journeys.
However, these requirements apply to Schengen visa applications and should not be interpreted as a universal insurance obligation for every foreign tourist entering Europe.
The distinction matters for Americans because U.S. citizens generally qualify for visa-free short visits within the Schengen Area, subject to the applicable 90-days-in-180-days limit and other entry conditions.
Visa-Exempt Americans Are Not Automatically Subject to the €30,000 Rule
American citizens on ordinary qualifying visa-exempt travel within the Schengen Area generally do not need to submit a Schengen visa application, so the Visa Code’s insurance documentation requirements do not automatically apply to their visits.
This distinction is often misunderstood when travel information websites describe the €30,000 insurance threshold without explaining that the legal requirement applies only within a specific visa application framework.
A United States passport holder visiting France, Germany, Italy, or Spain for a qualifying short stay should therefore distinguish recommended medical protection from the proof of insurance required under Schengen visa procedures.
Nevertheless, a visa exemption does not eliminate all immigration conditions, and national long-stay visa, residence, educational, or employment programs may impose separate insurance requirements.
Americans should also recognize that insurance can remain financially important even when it is not mandatory, especially because medical treatment abroad may be expensive and access to familiar domestic coverage may be limited.
Georgia Introduced Mandatory Tourist Insurance in 2026
Georgia provides an important contrast because its government introduced compulsory health and accident insurance for tourists entering the country beginning January 1, 2026, tying the requirement to tourist admission rather than a traditional visa application.
According to the Georgian government’s official consular guidance, tourists generally must possess insurance providing at least 30,000 Georgian lari in coverage, with policies available in Georgian or English.
The requirement recognizes policies issued by qualifying Georgian or foreign insurance companies and allows travelers to present the relevant documentation in either electronic or physical form during immigration examination.
The insurance must cover the entire visit, including arrival and departure dates, and include required information about the insured parties, coverage territory, insured risks, policy validity, and applicable financial limits.
Certain categories are exempt under Georgian regulations, so travelers should review the specific legal conditions rather than assume every international visitor is subject to the same rules.
Georgia Demonstrates Why Visa Exemption Does Not Eliminate Insurance Duties
United States citizens generally benefit from visa-free visitor arrangements when traveling to Georgia, but those immigration privileges do not independently exempt ordinary American tourists from the country’s compulsory insurance framework.
This distinction shows how governments can separate the visa requirement from the obligation to maintain appropriate health coverage during a temporary visit.
A traveler may therefore qualify for entry without an advance visa while still needing to present a valid insurance policy satisfying the prescribed coverage amount and documentation standards.
Georgia’s 2026 reforms also illustrate why historical travel advice may become unreliable, since information published before the new insurance rules took effect may incorrectly suggest that coverage remains entirely optional.
Americans planning travel to Georgia should verify the insurance requirements for their intended dates and immigration status, especially when purchasing policies from companies outside the country.
Cuba Maintains Separate Medical Insurance Requirements
Cuba is another destination with mandatory medical insurance requirements, though travel arrangements for American citizens involve additional legal conditions tied to U.S. restrictions on travel-related transactions.
The U.S. Department of State advises that Cuba requires visitors to have non-U.S. medical insurance and explains that qualifying coverage is ordinarily included in tickets for flights departing from the United States.
American travelers should still confirm their insurance arrangements with their airline, especially when itineraries involve indirect routes, extended stays, or circumstances that may affect the scope of coverage.
The Department of State also explains that coverage tied to certain airline arrangements generally applies for an initial 30-day period, so travelers staying longer may need additional protection.
Consider these rules alongside United States sanctions requirements, because appropriate medical insurance alone does not establish that an American’s travel to Cuba is authorized under United States law.
Insurance Requirements Differ From Financial Recommendations
A destination may strongly recommend travel medical insurance without making it a legal condition of admission, creating an important distinction between prudent financial preparation and an enforceable immigration requirement.
Government travel advisories often encourage Americans to obtain coverage for emergencies, hospitalization, and medical evacuation because unexpected treatment abroad can create expenses travelers must pay personally.
However, advisory language recommending insurance should not automatically be treated as a statutory requirement, especially when the destination does not request insurance certificates for ordinary visa-exempt travel.
Similarly, an airline or tour operator may impose contractual insurance requirements that differ from immigration rules, so travelers must identify which organization is responsible for the condition.
Travelers should distinguish between government admission requirements, commercial booking conditions, and personal financial protection before deciding what coverage they need for their journeys.
Travel Medical Insurance and Trip Cancellation Insurance Are Different
Travel insurance products can include several types of protection, but medical coverage and trip cancellation benefits serve different purposes and should not be treated as interchangeable when evaluating immigration requirements.
Travel medical insurance generally covers eligible healthcare expenses during a covered international journey, including emergency treatment, hospitalization, and medically necessary transportation, under the terms of the policy.
Trip cancellation insurance instead covers qualifying financial losses when a traveler cancels prepaid arrangements for reasons covered by the insurance contract, such as illness or other specifically defined events.
A comprehensive policy may combine both categories, but immigration authorities reviewing mandatory medical insurance generally require evidence of relevant healthcare coverage rather than proof that flights or hotels are insured.
Americans should therefore review policy wording carefully to determine whether the coverage addresses the specific medical risks and financial limits required by the destination government.
Medical Evacuation Can Create Significant Financial Exposure
Emergency medical evacuation is a key consideration because transporting an injured or seriously ill traveler to an appropriate medical facility can far exceed ordinary outpatient treatment costs.
Some travel insurance policies provide emergency transportation to the nearest suitable medical facility, while others offer additional repatriation benefits subject to medical necessity, insurer approval, geographic restrictions, and contractual coverage limits.
The distinction matters because a policy advertising substantial emergency medical coverage may not include equivalent evacuation protection, especially when travelers visit remote destinations or participate in adventure activities.
Americans should also examine whether the insurer coordinates transportation directly or requires the traveler to arrange services and subsequently request reimbursement under the policy’s claims procedures.
When immigration authorities require medical repatriation coverage, applicants should ensure the policy expressly includes the required benefit rather than assuming general emergency healthcare protection automatically satisfies the regulation.
Medicare and Domestic Health Plans May Offer Limited Overseas Protection
Americans relying on domestic healthcare arrangements should check whether their existing coverage extends to international travel, since standard U.S. health insurance may offer limited benefits or exclude certain expenses incurred abroad.
Original Medicare generally does not cover healthcare received outside the United States, except in narrow circumstances, although certain supplementary plans and private insurance arrangements may provide additional international benefits.
Employer-sponsored policies can also differ substantially, with some covering eligible emergency treatment abroad while others impose network limitations, reimbursement procedures, or restrictions on medical evacuation.
Travelers should confirm coverage with their insurer before departure, especially when planning extended journeys or visiting countries where healthcare providers require payment before treatment.
Existing domestic insurance should not automatically qualify as travel insurance when a destination specifies particular coverage amounts, benefits, policy dates, or documentary requirements.
Long-Stay Visas Can Have Separate Insurance Conditions
Insurance requirements for extended residence often differ from those for ordinary tourism because applicants may need to show ongoing access to healthcare for a much longer period abroad.
Retirement permits, student visas, employment authorizations, and family residence programs can establish different standards concerning acceptable insurers, healthcare benefits, coverage exclusions, and the duration for which protection must remain valid.
Some governments require locally recognized health insurance, while others accept qualifying international policies or establish alternative arrangements through public healthcare enrollment and employer-sponsored coverage.
An American applying for long-term residence should therefore avoid assuming that a short-term tourist policy automatically satisfies the requirements of a residence permit or national immigration program.
The right documentation depends on the specific authorization requested, so current government instructions are essential when comparing temporary travel insurance with longer-term healthcare arrangements.
Policy Dates Must Correspond With the Intended Journey
Travelers subject to mandatory insurance requirements should ensure their policy remains valid for the period specified by the destination, including arrival and departure dates.
A policy that begins after the scheduled arrival may leave a gap in protection, while coverage that expires before departure can create difficulties even when the insured amount otherwise meets the applicable financial threshold.
Changes to airline reservations, accommodation arrangements, or authorized stay periods may therefore require reviewing the policy and, where necessary, obtaining an extension or replacement document.
Travelers should also distinguish the insurance purchase date from the effective date of coverage, since some policies include waiting periods or restrictions that affect benefits purchased after travel begins.
Accurate policy dates matter especially in destinations such as Georgia, where the government expressly requires coverage for the tourist’s entire visit.
Adventure Activities May Require Additional Coverage
Americans traveling abroad for skiing, mountaineering, scuba diving, trekking, or other potentially hazardous activities should review insurance exclusions because standard travel medical policies may not cover every recreational pursuit.
Some insurers distinguish conventional tourism from higher-risk activities and require additional premiums or specialized endorsements for certain injuries, rescue expenses, or medical evacuations to be eligible for reimbursement.
A policy that meets a destination’s minimum insurance requirement may therefore offer less practical protection than travelers expect when a claim arises from an excluded activity.
Travelers should consider both the destination’s legal coverage conditions and the actual risks of their intended activities before selecting insurance.
The central question is whether the policy provides meaningful protection for the proposed journey rather than merely producing a certificate displaying the minimum amount required by immigration authorities.
Insurance Certificates Must Accurately Identify Coverage
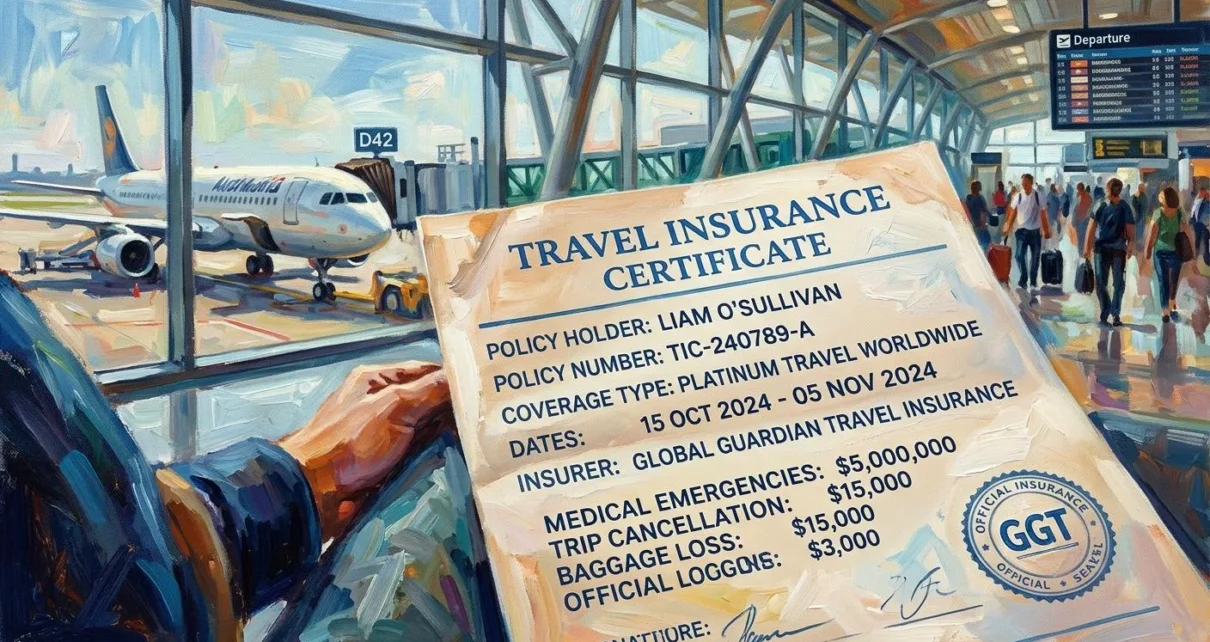
Where an immigration authority requires proof of insurance, the document may need to identify the insured traveler, policy provider, covered territory, effective dates, financial limits, and relevant benefits.
An insurance payment receipt alone may not show that the policy meets these conditions, especially where the destination requires a formal certificate or specific information about medical and accident coverage.
Travelers should obtain genuine records from their insurer and confirm the information matches the passport and itinerary used for the international journey.
Altered certificates, misleading statements about coverage, or documents issued for a different individual can create insurance and immigration complications that extend beyond ordinary administrative delays.
Clear documentation helps authorities confirm compliance while reducing uncertainty about the protection available during the visitor’s stay.
Passport Security and Insurance Verification Serve Different Functions
Electronic passports incorporate authentication technologies designed to support reliable identification, but these security features do not establish whether the holder possesses qualifying travel medical insurance or satisfies applicable healthcare coverage requirements.
Immigration authorities may therefore examine a genuine passport alongside separate insurance documents, financial records, and other information required under the destination’s admission procedures.
Amicus International Consulting examined the broader distinction between passport identification and supplementary travel documentation in Mexico’s Children’s Passports Include Parents’ Photos to Strengthen Travel Security, explaining how official records can address different verification requirements.
Although that analysis concerns parental identification rather than medical insurance, the underlying principle remains relevant because authentic identification and compliance with separate immigration conditions represent different elements of lawful international travel.
A successful biometric or electronic passport examination should therefore not be mistaken for evidence that every additional insurance or admission requirement has been satisfied.
Americans Should Verify Insurance Requirements Before Departure
Travelers should determine whether insurance is legally mandatory for their nationality and entry category before purchasing policies or relying on statements concerning universal international coverage requirements.
If insurance is required, the appropriate policy should meet the destination’s minimum benefits, financial limits, validity period, and documentation standards while aligning with the intended itinerary.
When insurance is optional, Americans should still assess their personal exposure to overseas medical expenses, especially when existing domestic coverage offers limited international benefits.
Official immigration guidance should take priority over generalized travel advice because countries can introduce or modify insurance rules independently of their visa exemption arrangements.
Careful preparation helps distinguish legally necessary documentation from additional protection that travelers may reasonably choose for financial and medical security.
Conclusion: Insurance Obligations Depend on the Destination
Travel insurance requirements for United States citizens vary by destination, immigration category, and applicable legislation, so universal claims about mandatory medical coverage or minimum insurance amounts are unreliable.
Schengen visa requirements show that insurance can be mandatory for a specific application category without automatically applying to American tourists traveling under ordinary visa-exempt arrangements.
Georgia’s compulsory tourist insurance rules, introduced in January 2026, offer a contrast, showing that visa-free eligibility does not necessarily eliminate separate medical coverage obligations imposed at entry.
Cuba’s medical insurance requirements further illustrate how destination-specific arrangements can interact with airline procedures, permitted travel activities, and restrictions relevant to American citizens.
Ultimately, responsible international travel preparation requires distinguishing visa requirements from entry conditions, confirming appropriate insurance protection, and recognizing that genuine medical coverage remains valuable even where the destination does not make it compulsory.